Why Is State Farm Dropping So Many Homeowners in Orinda?
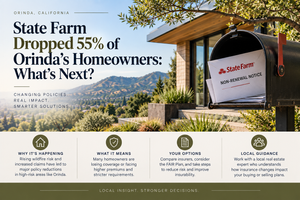
State Farm has non-renewed 1,703 of the 3,115 homeowner policies in Orinda's 94563 ZIP code — 55%, the highest concentration of any ZIP code in California. The decision is based on wildfire risk scoring, not claims history, so homeowners who have never filed a claim are losing coverage right alongside those who have. Neighboring Lafayette's 94549 ZIP is also on the affected list. If you're buying or selling in Lamorinda right now, this changes how you need to approach financing, contingencies, and timing.
By Michael Delehanty — Delehanty Group | DRE #01505346 | September 21, 2026
If you own a home in Orinda, there's better than a coin-flip chance State Farm just sent you a letter you didn't want. And if you're trying to buy or sell there this fall, that letter is now part of your transaction whether you like it or not.
What's Actually Happening
State Farm is the largest insurer in California, and it's pulling back hard from wildfire-adjacent ZIP codes across the state. Orinda got hit harder than anywhere else. Of the roughly 3,100 State Farm policies in the 94563 ZIP code, more than half — 1,703 — are being non-renewed. That's not a rate increase. That's the insurer walking away entirely.
A few things worth understanding about how this works:
- It's risk-based, not behavior-based. State Farm isn't dropping people because they filed claims. It's using wildfire risk modeling — First Street Foundation data puts 100% of Orinda properties at some level of 30-year wildfire risk — and non-renewing based on ZIP code and property characteristics, regardless of your history.
- You still get notice. California law requires at least 75 days' written notice before a non-renewal takes effect. That's your window to shop for replacement coverage before your current policy actually lapses.
- It's not just State Farm. Lafayette's 94549 ZIP is also affected, and other carriers have pulled back in Moraga and the Oakland Hills for the same wildfire-risk reasons. This is a market-wide retreat from the highest-risk parts of the East Bay, not one company's decision.
I covered the broader California home insurance crisis back in June, and the FAIR Plan's confirmed rate hikes since then. This is a different problem. That post was about the cost of staying insured through the state's insurer of last resort. This is about not being offered a private policy at all — which is a bigger issue for anyone financing a purchase.
What This Means If You're Selling in Orinda or Lafayette
If your own policy just got non-renewed, you're not alone, and you're not without options — but you need to move now, not after your 75-day window shrinks. More on that below.
If you're getting ready to list, though, there's a second angle to think about: your buyer's insurability, not just yours.
Here's the real transaction risk. About 13% of California real estate agents reported a 2026 deal falling out of escrow specifically because the buyer couldn't secure insurance before closing — and agents working Orinda, Moraga, and other wildfire-interface parts of the East Bay say it feels higher than that locally. If your buyer can't produce an insurance binder, their lender won't fund the loan. It doesn't matter how clean the rest of the file is. The deal dies at the finish line.
A few things that help on the seller side:
- Get ahead of it with your own documentation. If your home has any wildfire hardening — a Class A roof, ember-resistant vents, defensible space cleared to the current standard — have that documented before you list. It's exactly the kind of detail that can move a buyer's application from "declined" to "approved" with an admitted carrier, and it's worth stating in your listing materials.
- Expect longer escrows. An insurance-driven delay or fallout can effectively double the time it takes to get a home sold once it has to re-list. Build that into your pricing and timeline expectations rather than being surprised by it mid-transaction.
- Disclose what you know. If you've received a non-renewal notice yourself, or you're aware your ZIP code is on an affected list, that's relevant information for your own coverage continuity and worth discussing with your agent before you go under contract on your own purchase.
This is exactly the kind of wrinkle I walk sellers through before we set a list date — not to scare anyone off, but because a plan beats a surprise every time.
What This Means If You're Buying in Orinda or Lafayette
If you're house-hunting in Lamorinda right now, insurance needs to move from "something I'll figure out later" to "something I check before I write an offer."
Here's the order of operations that actually works:
- Get insurance quotes before you're in contract, not after. This is the single most common mistake buyers make, and it's the one most likely to blow up your timeline. Ask a broker to run your target property's address before you remove any contingencies — sometimes before you even write the offer.
- Understand the coverage ladder. If an admitted carrier — AAA/CSAA, Mercury, Farmers, or Kemper are still writing in parts of the East Bay — will still write the property, that's your best and cheapest option. If not, the next step down is a surplus lines (E&S) policy. If both decline, the California FAIR Plan is the guaranteed backstop, but it only covers fire, smoke, and a few related perils — you'll need to pair it with a Difference in Conditions (DIC) policy to cover everything a normal homeowners policy would, like theft, liability, and water damage.
- Ask what mitigation work has been done — or plan for what you'd need to do. Homes with documented wildfire hardening under the state's Safer from Wildfires program genuinely do better with admitted carriers. If a property doesn't have that work done, price the cost of doing it into your offer, not into a surprise six months after closing.
- Write your financing contingency with this in mind. Given how often insurance is now the reason deals fall apart, a slightly longer or more explicit financing/insurance contingency period is worth discussing with your agent — especially on a wildfire-interface property.
Walking a property the way I do — after 15 years running a contracting firm here in the East Bay — I'm looking at roof material, vent type, and defensible space just as closely as I'm looking at the kitchen. Those details used to be a nice-to-know. In Orinda and Lafayette right now, they can decide whether your loan closes.
This dynamic also compounds with a few things I've already written about — the same insurance-availability pressure is a big part of why mortgage payments have been climbing for Walnut Creek homeowners through escrow account shortages, and it's the same underlying risk factor behind why an outdated electrical panel can tank your insurability even outside a wildfire zone. If you're weighing Orinda against neighboring Lafayette or Moraga, insurance access is now a real part of that comparison, not a footnote.
The Bottom Line
State Farm's exit from more than half of Orinda isn't a one-off. It's the clearest, most concentrated example yet of a market-wide retreat from wildfire-risk ZIP codes across the East Bay, and Lamorinda is ground zero. Whether you're selling a home your family has owned for decades or trying to buy your first place in Orinda or Lafayette, insurance now belongs at the very front of your process — not somewhere near the end of it.
Your specific situation — your property's construction, your target ZIP code, your timeline — determines exactly how much runway you have and what your real options look like. That's not something a general article can tell you.
If you've gotten a non-renewal notice, or you're buying or selling in Orinda, Lafayette, or Moraga and want to know what to check before you remove contingencies, I'm happy to walk you through it. Text or email me directly — (510) 697-3900 or michael@delehantyre.com — and we'll talk through your specific address and timeline.
Frequently Asked Questions
Why did State Farm stop renewing homeowners in Orinda specifically?
State Farm's non-renewals are based on wildfire risk modeling, not individual claims history. Orinda's 94563 ZIP code has the highest concentration of non-renewals of any ZIP code in California — 55% of its roughly 3,100 State Farm policies — because First Street Foundation data shows essentially all Orinda properties carry some level of 30-year wildfire risk.
Can I still get homeowners insurance in Orinda or Lafayette after a non-renewal?
Yes, but it usually takes more work and costs more. Start by shopping remaining admitted carriers, then surplus lines (E&S) coverage if none will write the property, and the California FAIR Plan as the final backstop — paired with a Difference in Conditions policy since the FAIR Plan only covers fire and a few related perils.
How much notice does an insurer have to give before non-renewing my policy in California?
California law requires at least 75 days' written notice before a homeowners policy non-renewal takes effect. That window is your opportunity to shop for replacement coverage before your current policy actually lapses.
Will a State Farm non-renewal in my ZIP code affect my ability to sell my house?
It can, mainly by affecting your buyer's ability to get financed. Roughly 13% of California agents reported a 2026 deal falling out of escrow specifically over insurance, and lenders won't fund a loan without a bound policy in place. Sellers who document any wildfire hardening on the property before listing tend to see fewer financing-related surprises.
What can I do to make my home more insurable in a high-fire-risk area?
Documented mitigation under California's Safer from Wildfires program — a Class A fire-rated roof, ember-resistant vents, and defensible space cleared to current standards — can move a property back toward admitted-carrier eligibility and may qualify for premium discounts even on FAIR Plan policies.
About Michael Delehanty — Delehanty Group | DRE #01505346
Michael Delehanty is a Walnut Creek-based real estate agent with Compass, specializing in buying and selling homes across the East Bay — including Walnut Creek, Concord, Pleasant Hill, Danville, Orinda, and the surrounding communities.
Before becoming a real estate agent, Michael spent 15 years running his own contracting firm in the East Bay, working on thousands of homes and major projects across the Bay Area. That hands-on construction background gives his clients a distinct advantage: when Michael walks through a property, he sees what most agents simply can't. From structural details to renovation potential, his experience translates directly into sharper pricing, smarter negotiation, and fewer surprises at the inspection table.
Michael has been a licensed Realtor since 2005, bringing more than 20 years of experience to every transaction. He has successfully guided clients through complex situations including short sales, bank-owned properties, investment transactions, and competitive multiple-offer scenarios. Whether you are a first-time buyer, a move-up seller, or an investor, Michael brings the market knowledge and problem-solving skills to get deals done.
What sets Michael apart is his deep roots in this community. He has lived in Walnut Creek for nearly 30 years and is genuinely invested in the people here — not just the properties. He served four years as Auction Chair and Athletic Boosters President at Las Lomas High School, and has been a member of a local book club for eight years. His two daughters grew up here, attending Las Lomas before going on to the University of Washington and Cal Poly San Luis Obispo. When Michael helps you buy or sell a home in Walnut Creek or the surrounding East Bay communities, he is not just doing a transaction — he is working in the neighborhood where he has built his own life.
michael@delehantyre.com | (510) 697-3900 | michaeldelehanty.com