Should you sell before buying in the East Bay?
For most owners, selling first is the lower-risk path, because you know your proceeds and you never carry two housing costs at once. Buying in the East Bay before your home sells can still work when your lender approves you with both homes counted, when you have bridge financing, or when a seller will accept a sale contingency. Which one fits depends on your equity, your income, and how fast your specific neighborhood moves.
By Michael Delehanty — Delehanty Group | DRE #01505346 | November 10, 2026
Key Takeaways
- Walnut Creek homes sold over roughly the last 90 days as of November 2026 went under contract in a median of 14 days, so a contingent offer often competes against cleaner ones.
- Selling first gives you known proceeds but may require a rent-back, short-term rental, or storage if your next home isn't ready.
- Buying first means qualifying while you carry the current home's mortgage, taxes, insurance, and upkeep, and a lender may not count your expected sale proceeds until the home is under contract.
- A sale contingency protects you from owning two homes, but it can make your offer less competitive, and its terms are negotiated in each contract.
- Bridge financing is a lender product, not a right, and its qualification standards and repayment terms vary from lender to lender.
How does buying in the East Bay work when you still own a home?
You have three basic paths: sell first, buy first, or write an offer that depends on your sale. Each one moves the risk to a different place, and you want to know where yours lands before you tour a single house.
What happens if you sell first?
Selling first gives you certainty about your money and uncertainty about your housing. You know exactly what you're bringing to the next purchase, and you never pay for two homes at the same time.
The trade-off is timing. If your next home isn't ready when your sale closes, you may need a rent-back, a short-term rental, or storage. A rent-back lets you stay in the home you sold for an agreed period, but the possession date, insurance responsibilities, and security arrangements all have to be written into the contract.
If you go this route, I'd have the home inspected before it hits the market. With 15 years in contracting behind me, I'd rather you hear about the roof, the drainage, or the electrical panel from me than from a buyer's inspector in the middle of escrow, when it can put your closing date and your next purchase at risk.
What happens if you buy first?
Buying first protects your schedule but puts the most strain on your finances. You have to qualify while carrying the current home's mortgage, property taxes, insurance, and maintenance alongside the new payment.
A lender may underwrite the new purchase without counting your expected sale proceeds unless the current home is already under contract or you have enough income and assets to qualify without them. How that's treated is lender-specific, so get it in writing before you make an offer, not after. If your current loan has a low rate, that matters too, and I covered how it shapes decisions in my post on East Bay sellers and mortgage rates.
How does a sale contingency work?
A sale contingency makes your purchase depend on selling your existing home, so you can avoid completing the purchase if your sale falls through. The cost is competitiveness: a seller comparing your offer to one with no contingency may see yours as the riskier option.
Whether a seller accepts one, keeps marketing the property, or demands a kick-out clause is a contract matter and varies by transaction. If you use one, the contract should spell out:
- The deadline to list your current home
- Any minimum acceptable sale terms
- How and when notice must be given
- How it interacts with your inspection and loan contingencies
- Whether the seller can keep showing the property or invoke a kick-out provision
Is bridge financing or temporary housing the better fallback?
Neither is better across the board. Bridge financing keeps you to one move but adds debt tied to a sale price you don't control, while temporary housing costs you convenience but keeps your obligations clean.
What should you know about bridge financing?
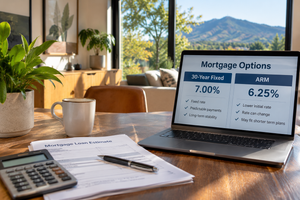
Bridge financing is a lending product, not a statutory right. It can supply temporary funds for a down payment or purchase before your current home closes, which can reduce the need for a sale contingency. That can make buying in the East Bay before selling a more realistic option when the neighborhood you want is competitive.
Qualification, maximum loan-to-value, reserves, interest rate, and the repayment period all depend on the lender and your underwriting. You also need a documented repayment plan. The sale proceeds usually pay it off, but neither the sale price nor the timing is guaranteed.
When does temporary housing make more sense?
Temporary housing makes sense when you'd rather accept a short stretch of inconvenience than take on extra debt or an overlapping mortgage. The risk is liquidity and timing: lodging, storage, and a second move can add up if your closing dates slip.
Whatever path you choose, the full cost picture has many parts: title and escrow services, lender charges, appraisal and inspection expenses, recording charges, prepaid taxes and insurance, moving and storage, temporary housing, and county transfer tax. Some of those are fixed and some are negotiable, and who pays what is set in your contract. Your title company can confirm the specifics, and I'll build you a personalized net sheet so you see your own numbers instead of a generic estimate.
How fast does the East Bay market move, and why does it matter?
It varies by city and price point, so a regional headline won't tell you how a contingent offer will be received. Metro-wide reports, such as the Realtor.com September 2026 report for the San Francisco-Oakland-Fremont metro, cover too wide an area to tell you how Concord or Danville behaves, and I wouldn't plan around them.
For a closer look, recent local market data for Walnut Creek shows homes sold over roughly the last 90 days as of November 2026 went under contract in a median of 14 days. During that window 303 homes sold, 240 homes are for sale now, and 94 new listings came on in the last 30 days. The median sale price in that window was $970,000, though your own home's value depends on its condition, street, build year, and timing.
That pace cuts both ways. A home priced and prepared well may sell quickly, which helps if you sell first. But the home you want probably won't wait for your sale either, and buying in the East Bay with a contingency means competing against offers that don't carry one.
| Area | Median Sale Price |
|---|---|
| Walnut Creek | $970,000 |
| Concord | $715,000 |
| Pleasant Hill | $901,000 |
| Danville | $1,861,500 |
| Orinda | $1,750,000 |
These are area-level medians, but they show why one plan doesn't fit every move. Going from Concord to Danville, or from Pleasant Hill to Orinda, changes how much of your down payment depends on your sale proceeds, and that changes which path is realistic. If you're still working out your budget, my post on East Bay home affordability in 2026 is a good place to start.
How do you choose the right path for your move?
Start with the numbers, not the house. Once a home you love is in front of you, every option starts to look more workable than it is.
- Get a written comparison from your lender of three scenarios: buying while keeping your current home, using bridge financing, and buying after your sale.
- Decide the longest overlap you can carry, meaning the number of months you could pay for two homes without strain.
- Line up a temporary-housing fallback before you need it, whether that's a rent-back, a short-term rental, or storage.
- Choose your offer strategy based on the specific neighborhood, not the regional headline. A contingent offer may be fine in one pocket and a long shot in another.
- Talk to me before you tour, so we know what your offer can realistically look like before you fall for a house.
Your answer depends on your equity, your loan, your timeline, and how your home will show to buyers. This is the kind of question I walk my clients through before we write an offer or list, because the right sequence is different for almost everyone.
If you'd like to see how past clients feel about working with me, you can read my reviews on Google and Zillow.
FAQ
Should I sell my East Bay home before making an offer on another house?
Selling first is the safer choice for most owners, because it gives you known proceeds and avoids paying for two homes. It isn't always the best fit, though. If you can qualify with both homes counted, or you have bridge financing, buying first may protect you from a rushed housing gap. A lender's written comparison will tell you which is realistic.
How does a sale contingency work in the Bay Area?
A sale contingency makes your purchase depend on selling your current home. The details are negotiated in the contract, including the listing deadline, notice requirements, how it interacts with your inspection and loan contingencies, and whether the seller can keep showing the property or use a kick-out provision. There's no standardized timeline, so every contingency is only as strong as its wording.
Will East Bay sellers accept an offer contingent on selling my current home?
Some will, but it often makes your offer less competitive. In a fast-moving area like Walnut Creek, where recent sold homes went under contract in a median of 14 days, a seller may prefer an offer with no contingency. It depends on the home, the other offers, and the seller's own timeline.
Is a bridge loan better than renting between homes?
Not automatically. A bridge loan avoids a double move and can help you make a stronger offer, but it adds debt and depends on a sale price and timeline you don't control. Renting or using a rent-back costs convenience but keeps your obligations simpler. Bridge terms vary by lender, so compare actual quotes before you decide.
What happens if my old home does not sell before my new-home closing?
You'll be responsible for both homes until the old one sells, unless your contract includes a contingency or you've arranged bridge financing. That means two sets of mortgage payments, taxes, insurance, and upkeep. This is why it's worth deciding in advance how long an overlap you can carry and what your fallback is if the sale takes longer than planned.
The bottom line on timing your move
Selling first, buying first, and using a contingency each put the risk in a different place: your housing, your finances, or your offer. The right choice comes from your numbers and the pace of your neighborhood, not from a rule of thumb. If you're thinking about buying in the East Bay and still own a home, schedule a conversation with me and we'll map out the sequence before you make any commitments. If you want to see what's available in the meantime, you can search homes here. If you're weighing a sale that may not cover your loan, my post on selling a Bay Area home for less than you owe covers that situation.
Equal Housing Opportunity. Michael Delehanty, Real estate agent licensed in California, Compass. Regulated by the California Department of Real Estate. This article is general information, not legal, tax, or financial advice. Confirm your own numbers with your title company, tax advisor, or lender.
About Michael Delehanty — Delehanty Group | DRE #01505346
Michael Delehanty is a Walnut Creek-based real estate agent with Compass, specializing in buying and selling homes across the East Bay — including Walnut Creek, Concord, Pleasant Hill, Danville, Orinda, and the surrounding communities.
Before becoming a real estate agent, Michael spent 15 years running his own contracting firm in the East Bay, working on thousands of homes and major projects across the Bay Area. That hands-on construction background gives his clients a distinct advantage: when Michael walks through a property, he sees what most agents simply can't. From structural details to renovation potential, his experience translates directly into sharper pricing, smarter negotiation, and fewer surprises at the inspection table.
Michael has been a licensed Realtor since 2005, bringing more than 20 years of experience to every transaction. He has successfully guided clients through complex situations including short sales, bank-owned properties, investment transactions, and competitive multiple-offer scenarios. Whether you are a first-time buyer, a move-up seller, or an investor, Michael brings the market knowledge and problem-solving skills to get deals done.
What sets Michael apart is his deep roots in this community. He has lived in Walnut Creek for nearly 30 years and is genuinely invested in the people here — not just the properties. He served four years as Auction Chair and Athletic Boosters President at Las Lomas High School, and has been a member of a local book club for eight years. His two daughters grew up here, attending Las Lomas before going on to the University of Washington and Cal Poly San Luis Obispo. When Michael helps you buy or sell a home in Walnut Creek or the surrounding East Bay communities, he is not just doing a transaction — he is working in the neighborhood where he has built his own life.
michael@delehantyre.com | (510) 697-3900 | michaeldelehanty.com