What Not to Do Before Closing on a Walnut Creek Home
What should you avoid doing before closing on a house in Walnut Creek?
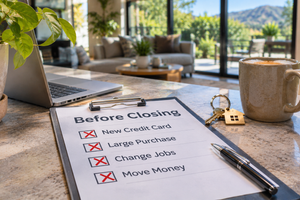
Until escrow closes, don't take on new debt, change jobs, move large sums of money without a paper trail, miss a bill, or remove your loan contingency before your lender has fully approved the loan. A pre-approval is not a final approval. Lenders typically re-check employment within 10 business days of closing and often review your credit again, so a car loan, a new credit card, or a job change in the middle of escrow can shrink or kill your approval. In California, removing your loan contingency too early can also put your deposit — often around 3% of the price — at risk.
By Michael Delehanty — Delehanty Group | DRE #01505346 | November 16, 2026
Here's a call no agent wants to make. The inspection went fine, the appraisal came in, the moving truck is booked, and four days before closing the lender says the loan needs to be "re-reviewed." Almost every time I've seen that happen, it traced back to something the buyer did after their offer was accepted.
It's more common right now than you'd think. Redfin's October report found roughly 15% of pending home sales nationally fell out of contract — the highest share in its records outside the spring 2020 pandemic spike. Redfin also counted 36% of sold homes with at least one price cut, another record. Buyers have more leverage than they've had in years, but leverage doesn't help if your financing comes apart.
The Bay Area has held up better. Redfin's July data put the Oakland metro, which includes Contra Costa County, at about a 9.3% cancellation rate, versus 14% nationally. That still means close to one in ten deals here doesn't make it, and the ones that fail late are the most expensive ones.
Why your pre-approval isn't the finish line
A pre-approval is your lender's read on your file the day you applied. Final approval comes later, after underwriting re-verifies everything. Between those two points, a few checks happen that most buyers don't know about:
- Employment is verified again. On Fannie Mae loans, the lender must confirm a salaried borrower's job no more than 10 business days before the note date. For self-employed buyers, the window is 120 calendar days.
- Credit is often reviewed again. Many lenders re-pull credit or monitor for new accounts and inquiries before funding.
- Bank statements get updated. The lender wants to see the cash for your down payment and closing costs still sitting where it was, with every large deposit explained.
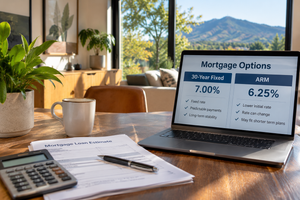
- Rates are moving. Freddie Mac's 30-year average was 7.11% on November 12, and futures markets are pricing in a Federal Reserve rate hike at the December 8–9 meeting. If your lock expires or your loan amount changes, your payment can change with it.
Here's why that matters at today's numbers. On a $900,000 Walnut Creek purchase with 20% down, a $720,000 loan at 7.11% runs about $4,844 a month in principal and interest. Add property tax and insurance and you're near $6,000. Many approvals at these prices are already built close to the lender's debt-to-income limit, so there isn't much room for anything new.
Seven things not to do until escrow closes
- Don't finance a car, furniture, or appliances. A new $800 car payment can move your debt-to-income ratio by several points on its own. If you need a new refrigerator for the house, buy it after you have the keys.
- Don't open or close credit cards. New accounts add inquiries and potential debt. Closing old cards can lower your available credit and nudge your score down. Leave everything exactly as it was.
- Don't change jobs, go part-time, or switch to commission or 1099 pay. Even a raise can be a problem if it changes how your income is calculated. If a job change is unavoidable, call your loan officer before you accept the offer, not after.
- Don't move money around without a paper trail. Don't shuffle funds between accounts, deposit cash, or accept money from family without documentation. Gift funds need a signed gift letter and transfer records. Every hop is another statement your underwriter has to trace.
- Don't miss or pay late on anything. One 30-day late payment can drop your score enough to change your pricing or approval. Set autopay on every account until closing.
- Don't co-sign for anyone. Co-signing a loan or lease puts that debt on your credit report, even if you never make a payment.
- Don't go quiet. Lenders ask for updated pay stubs, statements, and letters of explanation late in the process. A slow response can push your closing date past your rate lock or your contract's close of escrow.
One more that catches people: insurance. Your lender won't fund without a homeowners policy bound before closing, and in parts of the East Bay that can take time or cost more than expected. I covered how premiums can affect approval in how insurance costs can affect mortgage approval in Walnut Creek. Get quotes during your inspection period, not the week before closing.
The California piece: your loan contingency and your deposit
This is where a financing problem turns into a money problem. Under the standard California Association of REALTORS purchase agreement, the loan and appraisal contingencies run 17 days by default unless you negotiate a different period. In competitive East Bay situations, buyers often shorten them.
California contingencies don't just disappear when the deadline passes. You remove them in writing, usually on a contingency removal form. Once you've removed your loan contingency, not getting the loan is no longer a protected reason to cancel. If you and the seller both initialed the liquidated damages clause, the seller can typically keep your deposit, and California presumes up to 3% of the price is reasonable on a home you plan to live in. On a $900,000 home, that's up to $27,000.
So before you sign a contingency removal, ask your loan officer one direct question: "Is my loan fully approved, or is it conditionally approved with conditions still open?" If conditions are still open, find out exactly what they are and whether anything you're about to do could affect them. If you need more time, it's usually better to ask the seller for a short extension than to remove the contingency and hope.
Your other contingencies matter too. If the appraisal comes in short, you'll want options, and I walked through those in what to do about a low appraisal in Walnut Creek. And if the seller handed you a pre-listing report, my guide on whether Walnut Creek buyers should get their own inspection covers how to use your inspection window well.
Your closing-week checklist
The last stretch has its own steps. Federal rules require you to receive your Closing Disclosure at least three business days before you sign loan documents, so read it the day it arrives and compare it to your Loan Estimate. If the rate, loan amount, or cash to close looks different, ask right away.
- Confirm your lock date against your close of escrow, and ask what an extension would cost if escrow slips.
- Wire your funds safely. Call your escrow officer at a number you already have before sending money. Never trust wiring instructions that arrive by email alone.
- Know your cash to close. It includes your down payment, lender and title fees, and prepaid items. Our breakdown of buyer closing costs in Walnut Creek shows what to expect.
- Do your final walk-through to confirm the home's condition and any agreed repairs.
In my experience, buyers rarely lose a loan because of one big mistake. It's usually something small that felt harmless — a new card for the 10% off at the furniture store, a transfer between accounts, a job offer that seemed like good news. Over 20 years I've learned that the buyers who close smoothly are the ones who check with their agent and lender before they make any financial move at all.
Every file is different, and your lender's conditions are specific to you. This is exactly the kind of thing I walk my buyers through before we write an offer, so the timeline, the contingencies, and the financing all line up.
Frequently Asked Questions
Can a mortgage be denied after pre-approval?
Yes. Pre-approval is based on your file when you applied, and the lender re-verifies your income, employment, credit, and assets before funding. New debt, a job change, unexplained deposits, or a low appraisal can all reduce or cancel an approval.
Do lenders check your credit again before closing?
Many do. Lenders commonly re-pull credit or monitor for new accounts and inquiries before closing, and on Fannie Mae loans they must re-verify a salaried borrower's employment within 10 business days of the note date. Assume anything you do with your credit during escrow will be seen.
Can I buy furniture or a car before closing on my house?
Wait until after closing. New financing adds debt to your debt-to-income ratio and can push you past your lender's limit. Even paying cash can be a problem if it drains the funds the lender counted for your down payment, closing costs, or reserves.
What happens if my loan falls through after I remove contingencies in California?
You may lose your deposit. Once you've removed the loan contingency in writing, financing is no longer a protected reason to cancel, and if you initialed the liquidated damages clause the seller can typically keep up to 3% of the price on an owner-occupied home. Talk to your agent before signing any removal.
Can I change jobs while buying a house?
Talk to your loan officer before you accept a new job. Some changes, like a move to a similar salaried role, can work with an offer letter and paystub, while switching to commission, self-employment, or a probationary period can delay or derail the loan.
Getting to the closing table in Walnut Creek isn't about being perfect. It's about keeping your finances exactly as your lender approved them and not removing protections before your loan is truly ready. If you're trying to figure out what this means for your specific situation, I'm happy to walk you through it. Text or email me directly — (510) 697-3900 or michael@delehantyre.com — and we'll talk through the numbers. This is general information, not legal or lending advice, so confirm the details with your lender and, if needed, a real estate attorney.
About Michael Delehanty — Delehanty Group | DRE #01505346
Michael Delehanty is a Walnut Creek-based real estate agent with Compass, specializing in buying and selling homes across the East Bay — including Walnut Creek, Concord, Pleasant Hill, Danville, Orinda, and the surrounding communities.
Before becoming a real estate agent, Michael spent 15 years running his own contracting firm in the East Bay, working on thousands of homes and major projects across the Bay Area. That hands-on construction background gives his clients a distinct advantage: when Michael walks through a property, he sees what most agents simply can't. From structural details to renovation potential, his experience translates directly into sharper pricing, smarter negotiation, and fewer surprises at the inspection table.
Michael has been a licensed Realtor since 2005, bringing more than 20 years of experience to every transaction. He has successfully guided clients through complex situations including short sales, bank-owned properties, investment transactions, and competitive multiple-offer scenarios. Whether you are a first-time buyer, a move-up seller, or an investor, Michael brings the market knowledge and problem-solving skills to get deals done.
What sets Michael apart is his deep roots in this community. He has lived in Walnut Creek for nearly 30 years and is genuinely invested in the people here — not just the properties. He served four years as Auction Chair and Athletic Boosters President at Las Lomas High School, and has been a member of a local book club for eight years. His two daughters grew up here, attending Las Lomas before going on to the University of Washington and Cal Poly San Luis Obispo. When Michael helps you buy or sell a home in Walnut Creek or the surrounding East Bay communities, he is not just doing a transaction — he is working in the neighborhood where he has built his own life.
michael@delehantyre.com | (510) 697-3900 | michaeldelehanty.com